
The rumor mill was active last week with talk that the Obama administration is ginning up a plan to allow millions of homeowners to refinance their home mortgages to lower rates. The administration will not discuss details of the plan (and, in fact, won't acknowledge the existence of a plan), but it is expected to mirror a plan already proposed by Sens. Boxer (D-CA) and Isakson (R-GA) to target roughly 2 million "underwater" homeowners—those who owe more than their home is worth.
While the proposal may be politically advantageous for the President—it makes it look like he's doing something—it sounds like the proposal has limited prospects for success. Obama needs a plan that helps a lot of homeowners, stimulates the economy, and costs next to nothing. Let's see how the rumored plan stacks up.
A wave of refinancing could stimulate the economy because those who refinance would have smaller housing payments. In theory, they'd have extra money each month to spend on cars and big-screen TVs. Sounds nice, but the reality may be far different. Many of those people may just as soon use the extra money to pay down their credit cards or may need it for other essentials, or they may save the money given the deteriorating economy.
But let's assume it's a perfect world and all that extra money turns into consumer spending. Will it help enough people that it could stimulate the economy? Is it reasonable to expect that the administration can enact such a program?
To answer the first question, let's examine the reasons the existing program, the Home Affordable Refinance Program (HARP), has been so under-whelming.
The HARP program allows homeowners with loans owned by Fannie and Freddie to refinance homes that are as much as 25% underwater. It even ignores the homeowner's credit and job history. On a basic level, if the homeowner can document current employment and has been paying the mortgage on time, the homeowner is eligible.
Roughly 800,000 homeowners have taken advantage of the program, and I would argue most of the easy-to-refinance loans are done. Many did not qualify for HARP for the reasons below, and unless the new program addresses these issues, they still will not qualify.
- The homeowner must be paying the mortgage on time to be eligible, and it is likely the new plan will retain this requirement. Does it make sense to relax this requirement and refinance homeowners who cannot or will not pay their existing loans? If the homeowner is unemployed and cannot make the existing payment, a loan modification probably makes more sense. If the homeowner has simply stopped paying, why would we expect that a lower payment is going to induce payment? What's more likely is the homeowner is going to say, "This home is never going to be worth what I paid. I can rent a home down the street for the same payment, I don't have to pay taxes and insurance, and I can call the property manager when something breaks."
It might be reasonable to refinance homeowners who are current now but have made late payments in the last year (a disqualifying factor for HARP). It is possible the situation that caused the late payments - such as job loss - has been resolved. But how do you separate those who had cause for late payments from those who just found paying on time inconvenient? It raises an issue of fairness. And shouldn't we at least expect the homeowner to be current on the mortgage? That disqualifies all those folks who are behind on their mortgages unless they have funds to make up the missed payments.
- Many lenders have stricter guidelines for HARP because of the risk that Fannie and Freddie will make them buy back the loans if they go into default. For example, HARP says that homeowners can qualify even if their mortgage balance is 25% more than their home is worth. However, most lenders lower that limit to 5% because the temptation to walk away from a home 25% underwater is much greater. If the government wants lenders to adhere to the program parameters, it needs to remove the "buy back" risk.
- Many homeowners are under water because they used no or low down payment loans to purchase their homes. While market mortgage rates currently are 4.5% or less, these folks don't qualify for those rates. Fannie and Freddie "add-on" to the rates for those whose mortgage balance nearly equals or exceeds their property value. They also add-on to the rate for those with poor credit histories. These add-ons may add half a percent or more to the interest rate. While it certainly makes sense for someone to refinance a 6% rate to 4.5%, it doesn't look so attractive when the new rate is 5.25%. Certainly, the new plan could remove the add-ons, but, statistically, these loans are more likely to default. Isn't it appropriate to charge for that increased risk? (Otherwise, the risk is passed along to all homeowners through higher rates or paid by taxpayers through bailouts of Fannie and Freddie.)
- Homeowners who have second mortgages also have had trouble refinancing using HARP. HARP doesn't limit the allowable balance of a second mortgage used to purchase the home, but the second lien must be re-subordinated to the new mortgage. This usually isn't a problem in Texas. However, if the second lien is a home equity loan, the homeowner probably cannot qualify for HARP. Many of those underwater homeowners find themselves in this situation, and if the new plan does not address home equity second liens, these folks still will not qualify.
- Another group of folks cannot refinance because of the associated loan costs (closing costs and prepaid taxes, insurance, and interest). Freddie Mac limits the amount the homeowner can increase the loan balance to absorb these costs. For homeowners who pay their property taxes and insurance as part of their mortgage payments ("escrowing"), this is probably the worst time of year to refinance. The homeowners will need funds to pay a full year of property taxes at closing. (Of course, the homeowners will get these funds back from their current lender, but usually after closing.) A lot of folks just don't have $5,000 to plunk down at closing.
Even if the homeowner could include all the costs in the new loan, does that really make sense? If you have a mortgage that is $50,000 underwater, do you really want to increase the loan balance by $10,000 and put the homeowner that much further behind? If the homeowner defaults, the taxpayers are on the tab for not only the original mortgage, but also the homeowner's taxes, insurance, and closing costs.
One rumor has it that the new plan would eliminate closing costs. The homeowner would need only to log into a Web site and push a button. Voila. Instant refinance. Sounds nice, but even if Fannie and Freddie keep the loans in their portfolios, they still have costs associated with preparing the new loan documents and setting up loan servicing. Shouldn't they order a new title report to make sure they can foreclose, if necessary?(In Texas, title insurance isn't cheap.) Certainly, it doesn't make sense for Fannie and Freddie (i.e., taxpayers) to pick up these costs. And aren't Fannie and Freddie under orders to reduce their portfolios?
Besides, is it really fair to all those folks who paid thousands of dollars to refinance in the last couple years to offer a program now with no costs? If you'd only waited, the government would have picked up your closing costs.
- One final group of homeowners that generally has been unable to take advantage of HARP is the self-employed. The program requires lenders to document a borrower's ability to pay the new loan. Given the state of the economy, many self-employed reported reduced income last year, maybe even a loss. Any program that is going to help these folks will have to ignore the homeowner's income. Wouldn't it make sense that if the homeowners are paying the existing, higher payment that they will be able to pay the new, lower payment? But ignoring "ability to pay" flies in the face of current sentiment in Washington.
- Finally, HARP only applies to loans owned by Fannie and Freddie, and the new plan is likely to target these same, "government-owned" loans. This reduces the pool of target loans, but it also raises another fairness issue. Is it really fair for the government to spend money on a program to refinance your neighbor's loan and not yours? But expanding the plan to all loans is hard to conceive. The government sets the rules for Fannie and Freddie, but it has limited power over privately-owned loans.
There are several other hurdles to using HARP, but given the ones above, expecting the new plan to help two million homeowners is probably overly optimistic. Even if the plan does meet its target, industry groups estimate 10 to 17 million homeowners have underwater mortgages. That leaves a lot of struggling homeowners without help.
But, let's go back to our perfect world and assume the plan can overcome all these hurdles. What are the chances such a plan can be enacted? I suggest they are rather low.
Congress is not likely to go along with such a plan because someone has to pay for it. Throwing more money at the housing problem feels like tossing dollars into a furnace. Fannie and Freddie are still insolvent, and Congress seems more interested in getting them healthy so it can turn them loose than in using them to support housing policy. (We tried that for many years. Didn't we learn anything?)
But, you argue, it shouldn't cost Fannie and Freddie much to administer the plan, and lowering loan payments might reduce future foreclosures. The homeowners would refinance the full amount of their existing loans, so we have no principal reduction costs. So, what's the big deal?
Well, many of the mortgages that might be eligible for the plan are part of securities, and the price investors paid for those securities was based on expectations that only a fraction of the mortgages would be refinanced or paid off each year. (Rumors about the plan already have depressed the price of securities containing potentially targeted loans.) You say, "Screw the investors!" That's good populist sentiment, but you have to realize that some of those investors are pension and retirement funds. It's not just the rich that will pay the cost.
If Congress won't pass the President's plan, why can't he just tell Fannie and Freddie to do it? Well, that's not the way the government works. Fannie and Freddie are under the control of the Federal Housing and Finance Authority, an independent agency. Right now, it's headed by Ed DeMarco, a holdover from the Bush administration. Senate Republicans blocked Obama's nominee to head the agency when he expressed interest in using Fannie and Freddie for political purposes. DeMarco is more likely to agree with Congress that Fannie and Freddie need to stop tinkering with the housing market and work on their solvency.
I'm painting a pretty dim picture for enactment, and I may be all wrong. It's possible the President will be able to garner public sentiment to pressure Congress to support his plan. It's also possible, and call me a cynic, that the President's real plan is to blame Congress for failing to act when it refuses to pass a plan than simply won't work.

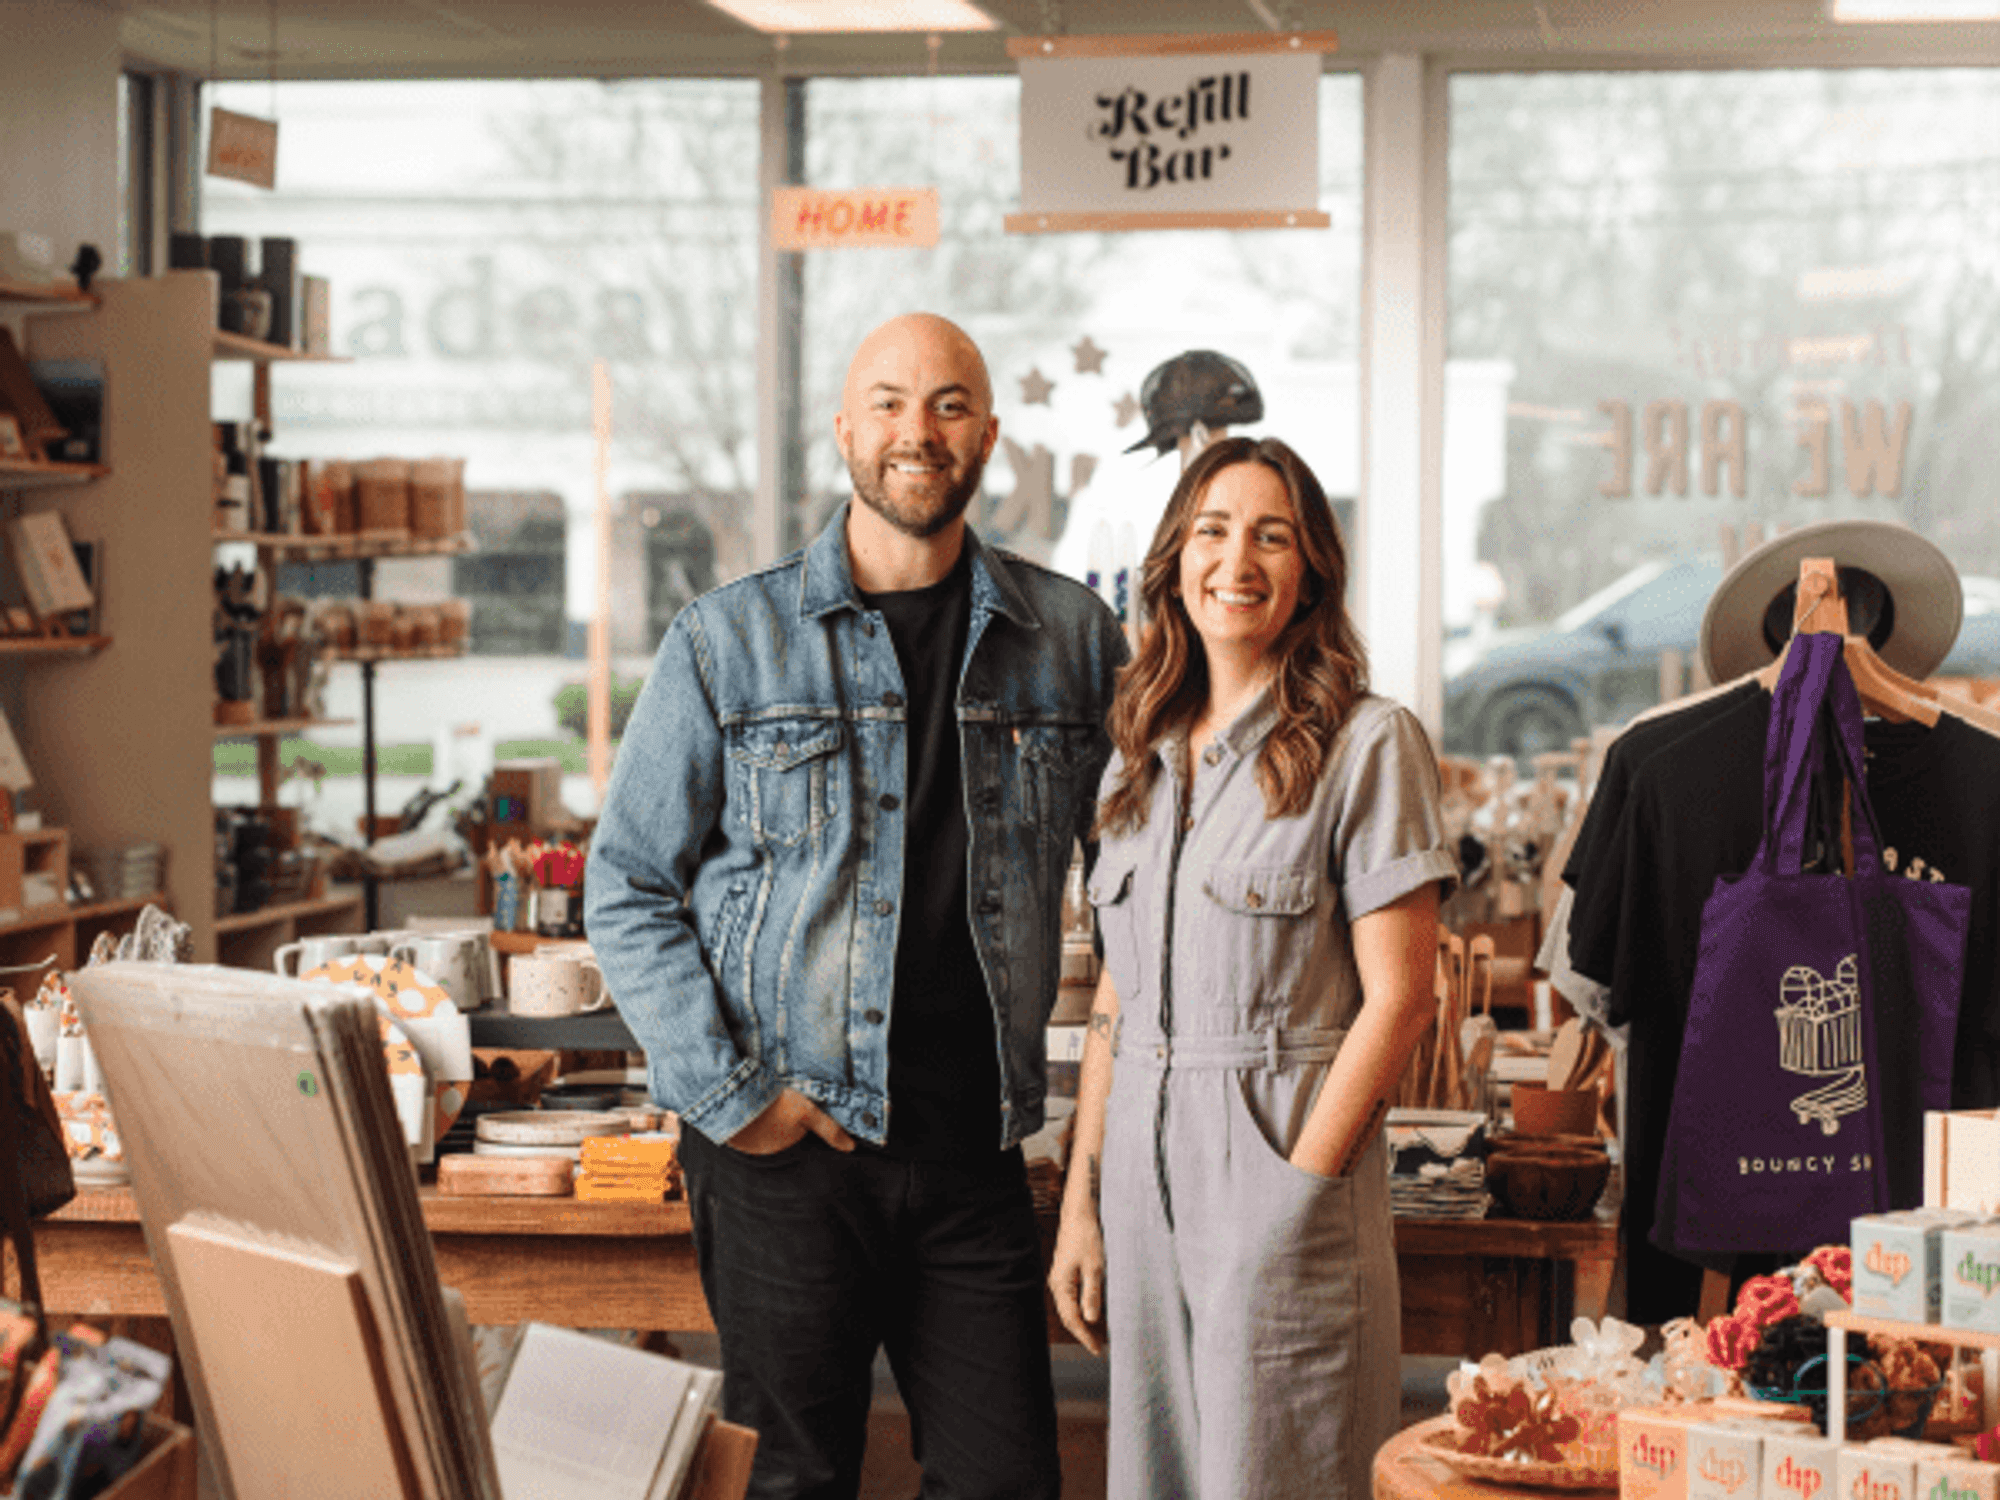
Austin's creative, low-waste general store Parker + Scott is getting very transparent this holiday season. Founders Jess and Ian Haisley calculated that they needed to make 3,439 sales by New Year's Eve to maintain their current business operations. To help track those sales, they've launched a new web app that turns shopping into a community challenge.
Both owners appeared in a video posted November 8 announcing the goal and the counter on social media. They explained that they want to start a conversation about the reality behind running a small business. November and December are big months for the business, so it's important that sales stay on track.
In a phone call with CultureMap, Ian Haisley assuages fears that Parker + Scott is on the verge of closure.
"No, it's not dire. These are, like, standard business operation numbers that we need to hit," says Haisley. "But the reality is, a bad November/December leads to a potentially dire January/February. So much of the business is dependent on those gift-giving seasons ... that if we have an under-performance, then things get tight."
"Getting tight," he clarifies, doesn't mean immediate closure. Instead, it's a "waterfall" of different decisions: holding off on things like on buying a new product, expanding hours, or hiring someone new.
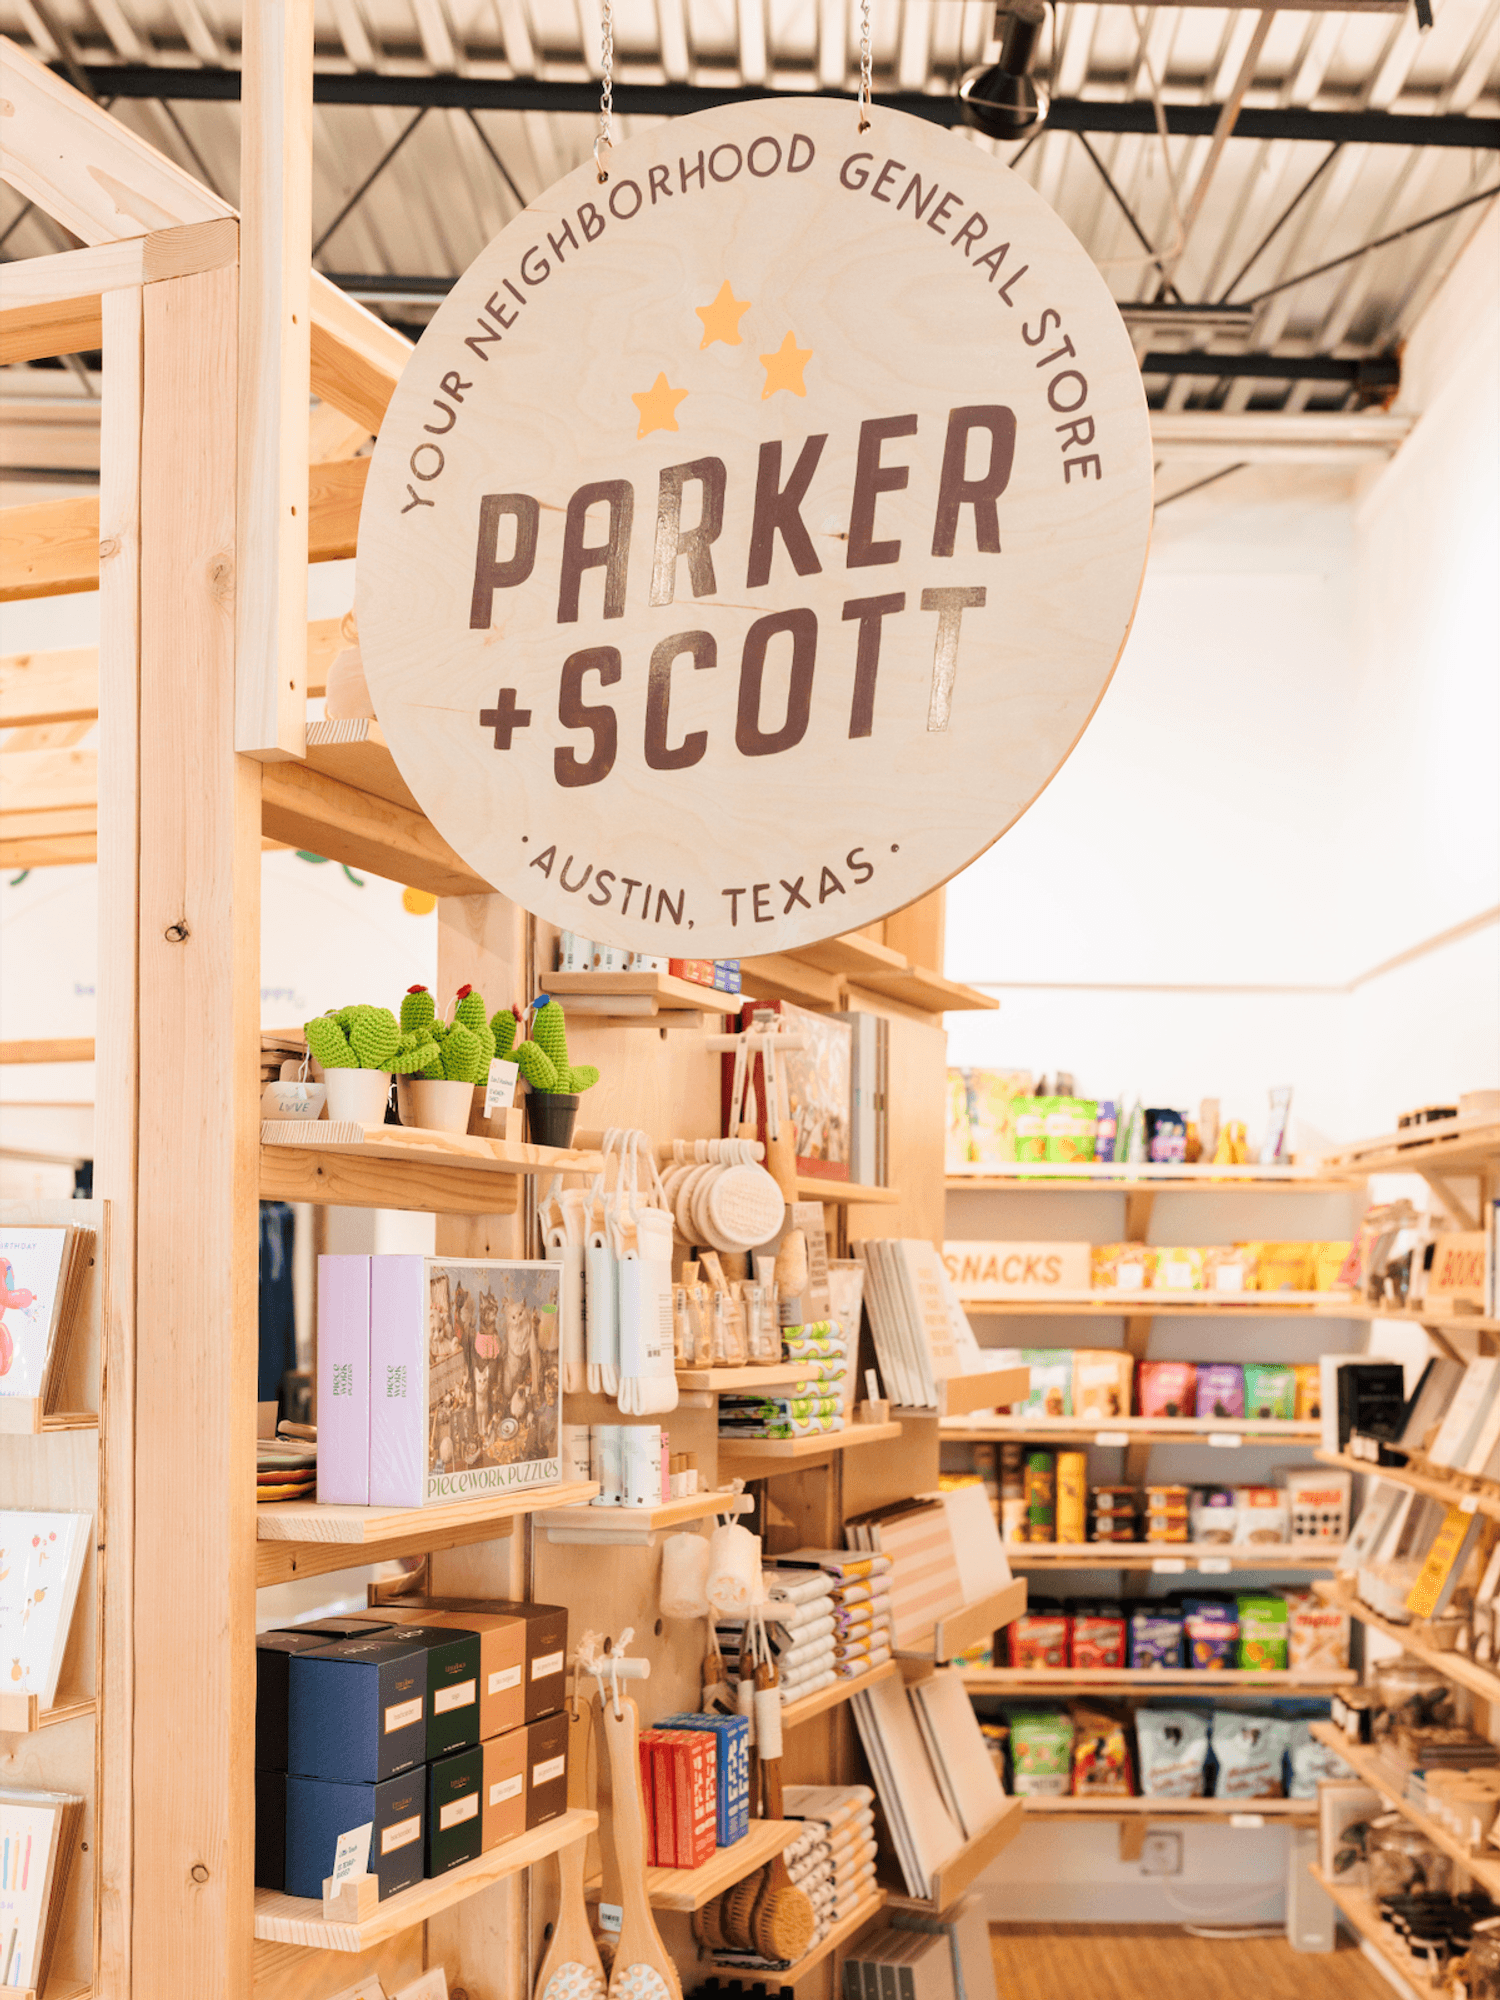 Gifts at Parker + Scott could be long-lasting, like a book, or gone before a party is over, like gourmet snacks.Photo courtesy of Parker + Scott
Where 3,439 comes from
To calculate the goal number of sales, Haisley found the store's average transaction amount in dollars from the past 24 months. When the couple announced the goal, they had 54 days left to hit it.
Haisley then used the vibe coding platform Lovable (which generates code based on user descriptions) to connect the store's Square account to a simple page that updates every 15 minutes. Near closing time on Wednesday, November 11, the recorded transactions had just passed the 200 mark. The site also shows how many sales happened that day, how many sales ahead or behind the store is, and how many days are left, plus a graphic representing the portion of the goal reached so far.
Transparency in local business
Letting customers see into the business in this way counteracts the public's tendency to assume that no news is good news for small businesses. He points out the impending closure of Dia's Market & Deli, one of the first stores the Haisleys shopped at when they moved from Austin to Chicago in 2020.
"We've seen [other small retailers] close, and seemingly it's out of the blue, right?" says Haisley. "I'm sure for them, much like for us, they're thinking about numbers on a daily basis, they're looking at stats constantly, but the announcement came, and it felt out of the blue. All of a sudden, for the first time ever, we hear that they've been struggling..."
Thankfully, Haisley says he and Jess are about to renew a five-year lease with a great rental rate — he knows because they consulted with their real estate agent and looked at other properties, just in case. Still, rent is a significant part of their budget, and it's all they can afford. Businesses in rented spaces are also always at risk of having to move if a property sells and is redeveloped.
Haisley says he thinks people who don't own a small business probably don't understand the full scope of overhead costs. Rent isn't the only cost. Before making any money at all, they also need to pay for an alarm and an internet bill, plus the majority of inventory in the store. (Some things, especially one-of-a-kind items by local makers like ceramics, are on consignment.)
Parker + Scott is best known in Austin for its refill bar, a table where shoppers can fill their own containers with household goods like shampoo, dish soap, and cleaning products. The store also specializes in plastic-free products, "better for you" options, and goods by local makers, especially women. A large snack section rounds out the shopping experience.
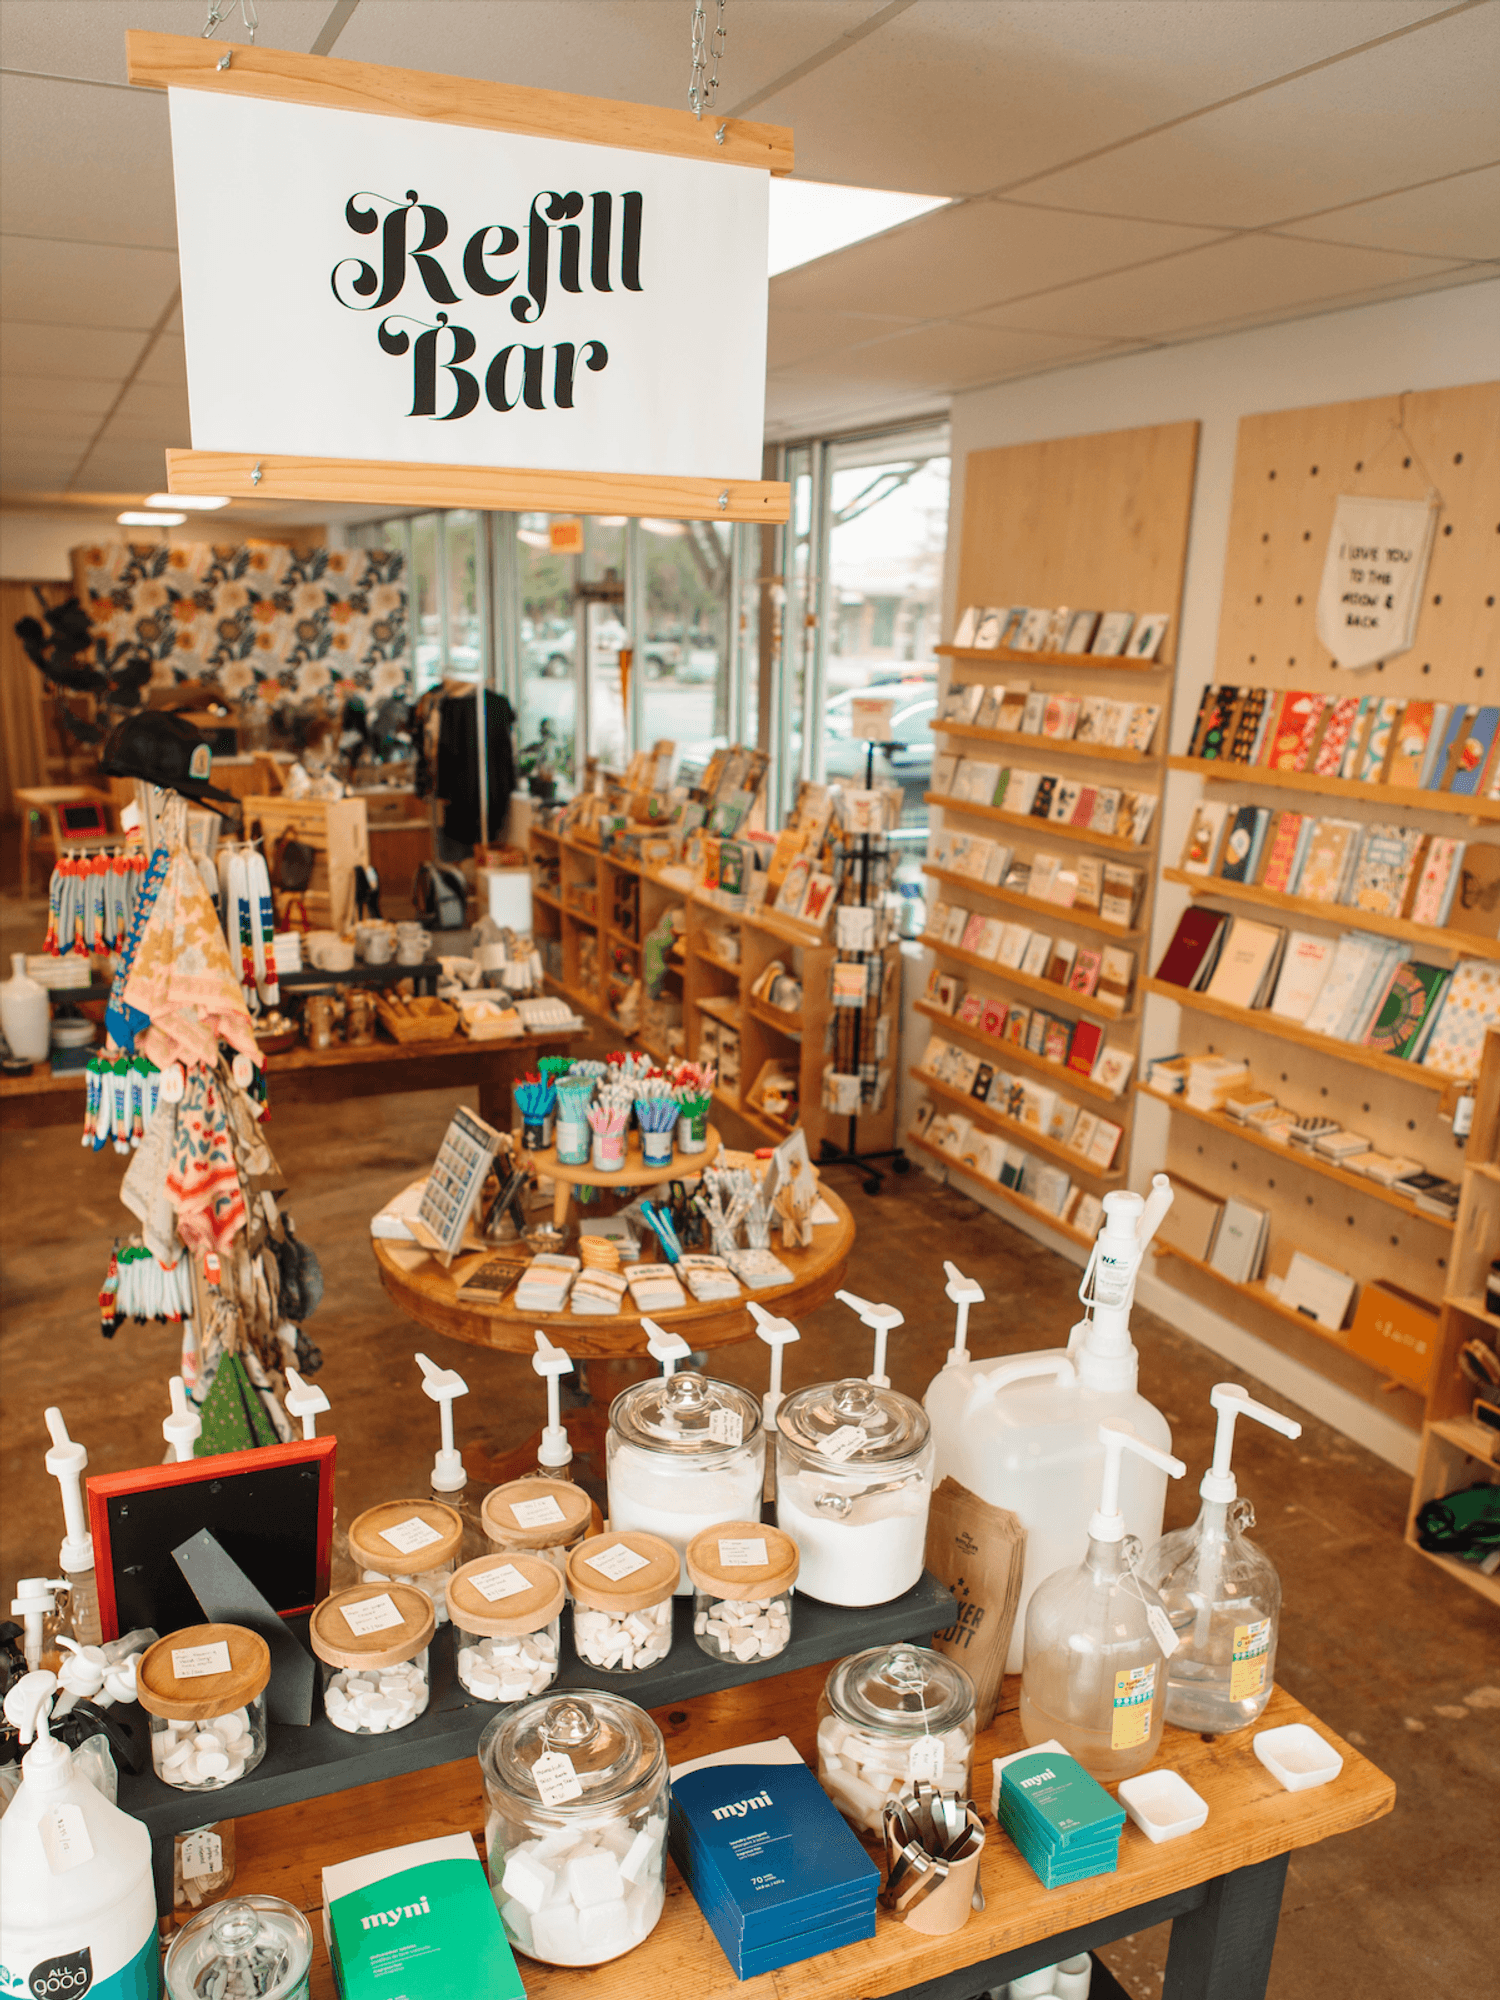 The refill bar is popular with customers who don't want to keep throwing away excessive packaging.Photo courtesy of Parker + Scott
Sometimes sustainable and thoughtfully made products end up costing more than their alternatives, but they are an integral part of the business. Haisley sees high demand for them, including at big retailers that are catching on. The refill bar is also good for business, because it draws in repeat customers, often as frequently as once a month.
Both owners are in the store often, keeping them connected to those regulars and other shoppers who happen to chat when they stop by. Haisley says he stocks a lot of new products by customer request. That kind of relationship makes it possible to move past stigma about hard business talk, and be honest about what the store needs to keep running smoothly.
"Because we're super invested in our neighborhood, super invested in the community, and we have really solid relationships, I think we see people far more frequently than a lot of shops might — which is something we work really hard to do," Haisley says.
Ideas for gift shoppers
Shoppers looking for gifts at the store will find plenty of new offers for inspiration. In the first update posted after the goal counter went live, the shop teased two new products: locally made functional chocolate by Haedyn ("hee-din"), and soy sauce made in Japan for a company based in Austin, called Dojo.
Haisley also says that curated gift boxes are coming back soon, and he's working on some blog posts to introduce readers to other popular products that make good gifts. Finally, he names some of Parker + Scott's small business neighbors that folks should check out while they're in the area: Blue Moon Glassworks, Sea of Beads, Birdhouse Books, Honey Hill Market, and Collected by Blackbirds.
"I don't know that everybody realizes how lucky we are to have so many unique shops and so many people who have taken a risk to put their retail dreams into reality...so like we should all be out there supporting them as much as we can," Haisley says. "They are unique shops that make Austin, Austin, and if we don't support them, they are going to disappear."
Parker + Scott is located at 2113 W. Anderson Ln., Ste B. Store hours are 10 am to 7 pm daily except Sundays, which are 11 am to 5 pm. Customers can also shop online at parkerandscott.com. Those sales also count toward the total goal.
